
HOW TAKING LOANS WITHOUT A REPAYMENT PLAN CAN AFFECT YOUR MENTAL WELLBEING
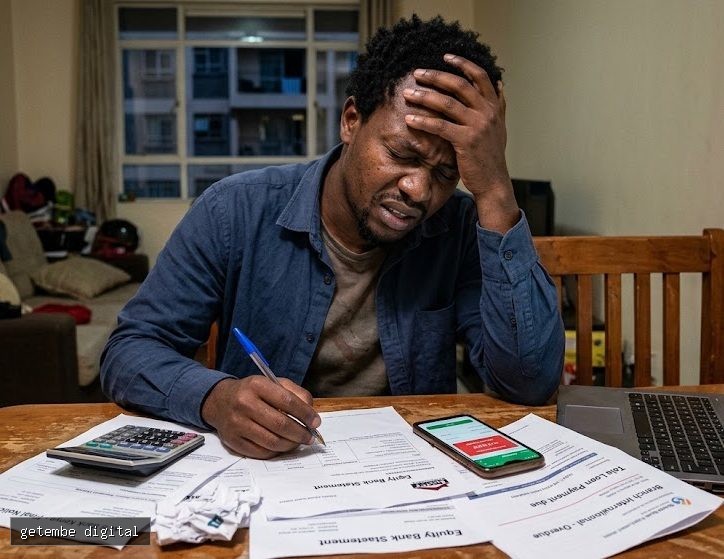
Taking loans without a realistic repayment plan can lead to financial stress, anxiety, poor sleep and emotional distress, especially when debts begin to accumulate.
Watch Getembe TV Live
Broadcast Getembe TV Live Stream
Listen Getembe FM Live
Tune in to Getembe FM Live Broadcast
Taking a loan can provide much-needed financial relief when used responsibly. However, borrowing money without a clear plan for repayment can expose an individual to financial pressure that may eventually affect their mental wellbeing.
Debt does not automatically lead to mental-health problems, but research has consistently linked problematic debt and financial stress with conditions such as anxiety, depression and emotional distress.
One of the immediate effects of unmanaged debt can be persistent worry. A borrower may constantly think about where the next repayment will come from, particularly when the loan instalments are due before they have sufficient income.
This uncertainty can make it difficult to concentrate on work, studies or daily responsibilities.
When a person takes one loan to repay another, debt can quickly become difficult to manage. Additional interest, fees and multiple repayment deadlines can increase financial pressure.
The feeling of being trapped in a cycle of borrowing can contribute to frustration, helplessness and emotional exhaustion.
Financial worries can follow people into the night. Concerns about overdue payments, calls from lenders or the possibility of losing access to essential services can make it difficult to relax or sleep properly.
Poor sleep can, in turn, affect concentration, productivity and a person's ability to make sound financial decisions.
Some borrowers may experience guilt or embarrassment when they are unable to repay their loans on time. They may avoid discussing their financial difficulties with family or friends, leaving them to deal with the pressure alone.
Social isolation can make financial stress feel even more overwhelming.
Without a realistic repayment strategy, borrowers may resort to taking additional loans to cover existing debts. While this may provide temporary relief, it can increase the overall financial burden.
This is why financial planning should come before borrowing. A borrower should consider their income, essential expenses, existing debts, interest rates and the amount they can realistically afford to repay each month.
Before taking a loan, it is important to ask whether the money is necessary, how it will be repaid and what will happen if income falls or an unexpected expense arises.
Creating a repayment budget can help prevent debt from becoming overwhelming. People who are already struggling with debt may also benefit from speaking to a trusted financial adviser, lender or support person rather than taking another loan simply to postpone the problem.
Ultimately, borrowing is a financial decision that can have consequences beyond the wallet. Having a realistic repayment plan can help reduce financial uncertainty and protect one's overall wellbeing.
ADVERTISEMENT
Watch Getembe TV Live
Broadcast Getembe TV Live Stream
Listen Getembe FM Live
Tune in to Getembe FM Live Broadcast
How do you feel about this article?
Let us know by choosing a reaction below.

Written by Anne Moses
Reporter and staff writer at Getembe News.
Comments 0
Please log in to participate in the comments section.
No comments yet. Be the first to share your thoughts!
ADVERTISEMENT
Related Stories


Have a news tip?
Do you have an investigation, local story or news event you think we should cover? Contact our newsroom directly.
Submit Tip
Mobile App
Download Getembe Digital App Today
Download Getembe Digital App today for live news updates, breaking notifications, and seamless live streaming.